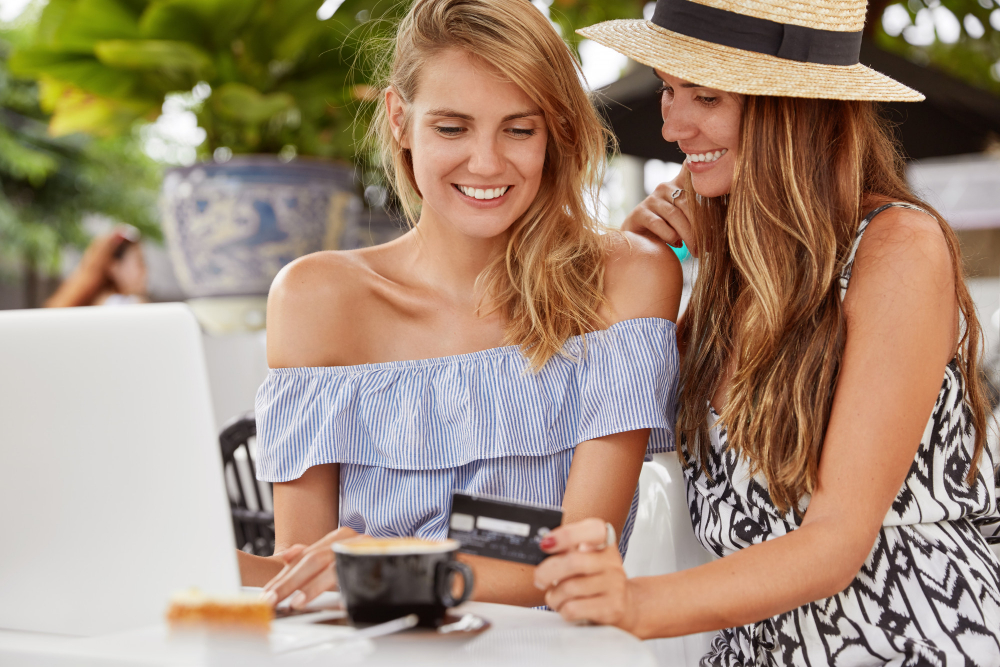
Opening a bank account, changing insurance or subscribing to a new streaming service: these procedures, once seen as simple formalities, have become for many French households a source of regular savings. The principle has long been known in the world of banking and insurance, but it has become widespread in recent years thanks to the proliferation of referral codes available in practically every area of everyday consumer spending.
The mechanism remains simple. An existing customer forwards a link or a personal code to a friend or relative, who in return receives a benefit upon signing up: a discount, a welcome bonus or credit on their first purchase. In return, the referrer also receives compensation, in the form of cash or vouchers. This positive-sum arrangement explains why retailers continue to invest in these schemes rather than in traditional advertising alone: the acquisition cost of a referred customer remains, in most cases, better controlled than a display campaign or a traditional ad placement.
Cashback platforms have followed a similar trajectory. They pass on part of the commission collected from partner merchants directly to the buyer, in the form of credit or bank transfer. Added up over months, this accumulation can represent a considerable amount on a household budget, particularly for recurring purchases such as online groceries, subscriptions or travel. Some households even maintain regular monitoring, tracking the periods when welcome bonuses are temporarily raised by retailers to attract new customers before the end of a commercial quarter.
This shift reflects a broader behavioral change. Consumers compare more, take the time to look for a code before checking out a cart, and now consider this step an almost natural reflex, on a par with searching for the best price. Online banks, energy suppliers and telecom operators have well understood this expectation: most now offer a structured referral program, with conditions clearly displayed and tracking of the referred person until the bonus is paid, sometimes supplemented by automatic email reminders.
That said, vigilance remains necessary. Not all offers are equal, some eligibility conditions remain restrictive, and an expired or incorrectly entered code can cause the promised benefit to be lost. As the official documentation of the Ministry of the Economy reminds, it is still useful to read the terms and conditions before committing rather than relying on a code found at random on a forum. This caution, coupled with clearer presentation of offers, largely explains why referral programs occupy an increasing place in the shopping habits of the French, without ever becoming the promise of quick enrichment, but rather one of recurring and cumulative savings, built month after month.
Profil de l'auteur
Derniers articles
 Everyday Life & Society14 September 2026L'invasion silencieuse : tout savoir sur les punaises de lit
- Everyday Life & Society7 September 2026Partager ses biens pour changer des vies
- Decoration & Furniture1 September 2026Transformer vos émotions en véritables pièces de décoration
- Everyday Life & Society24 August 2026Uri Poliavich : how to create technology companies and digital platforms
Table of Contents